
ACM Research is gaining share as China localises chipmaking tools, with non-cleaning equipment now driving more than half of sales despite mounting margin and concentration risks.
ACM Research is emerging as a beneficiary of China’s drive to build a more self-reliant semiconductor supply chain, and the company’s recent results suggest its gains are being driven by more than industry spending alone. In 2025, its mainland China revenue rose 15.8%, even as China’s overall semiconductor equipment market slipped by about 0.5%, according to industry analysis cited by The Information Network and echoed by Yahoo Finance. That divergence points to a supplier that is broadening its product range and winning more business from existing customers, rather than merely riding a cyclical upswing in capital expenditure.
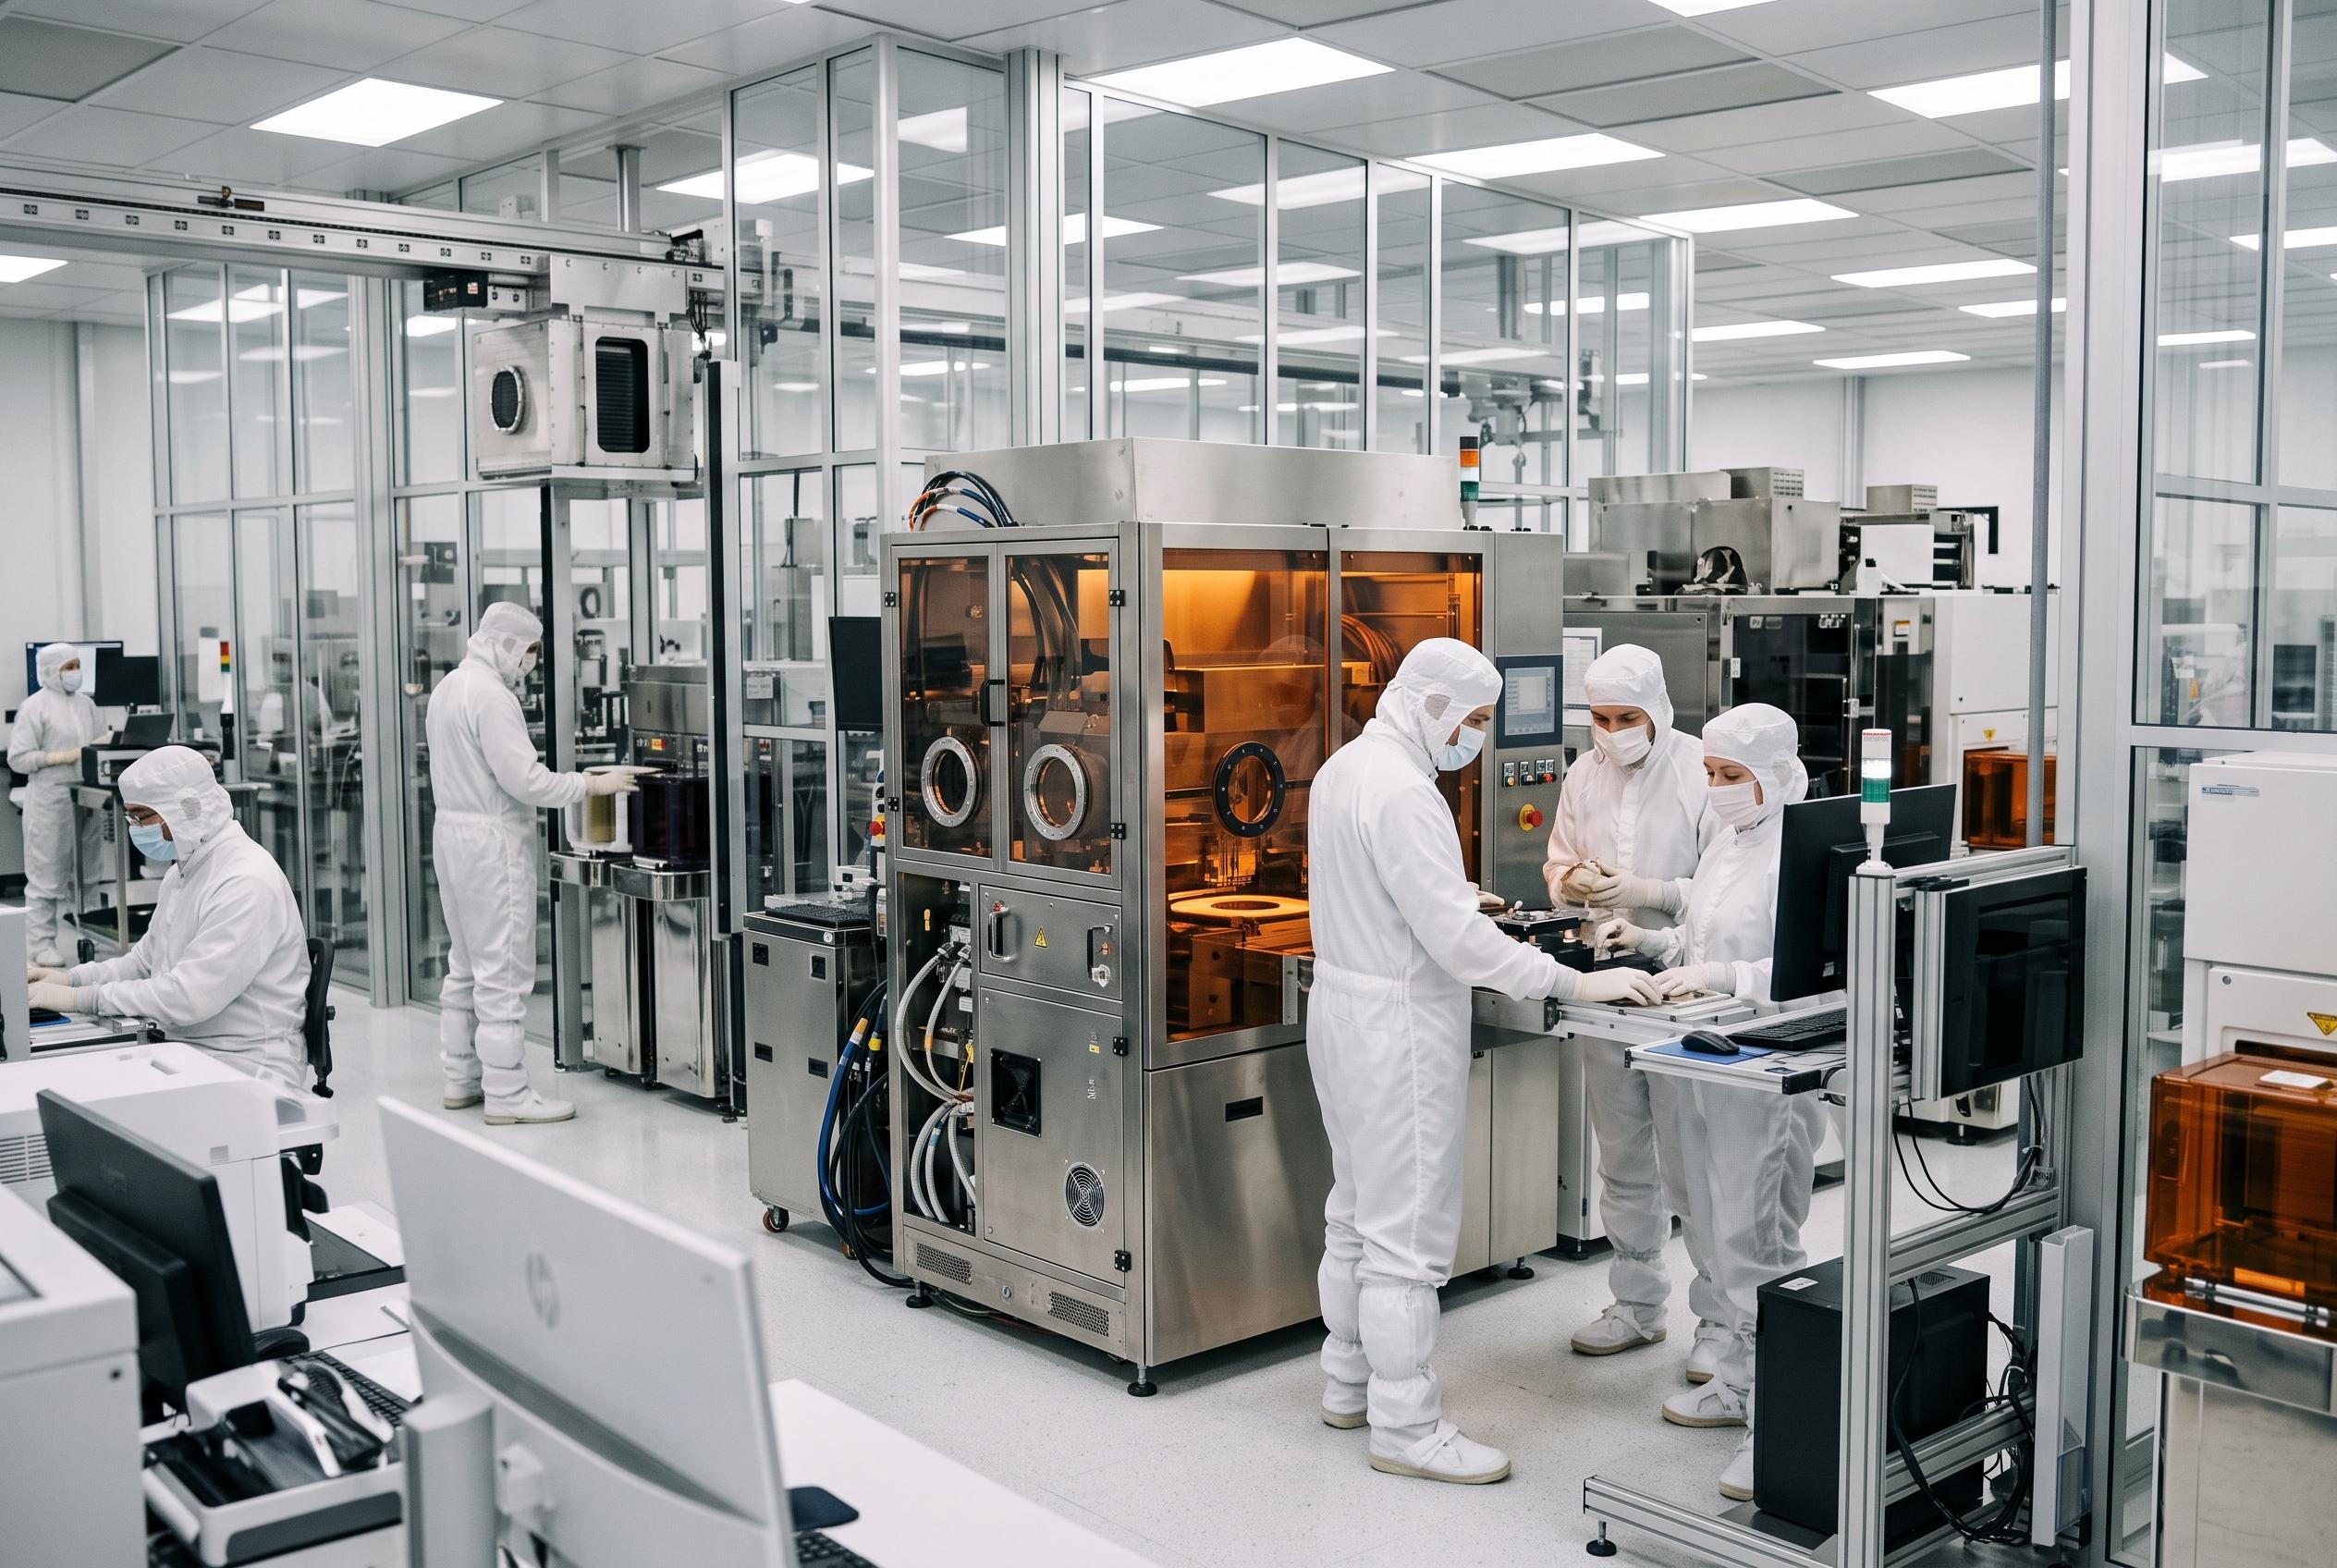
The broader context matters. Beijing’s push to reduce dependence on foreign chipmaking tools has encouraged domestic manufacturers to qualify local alternatives across wafer cleaning, deposition, etching, electrochemical plating and advanced packaging. Tom’s Hardware reported that Chinese chip equipment makers posted record revenues in 2025 as domestic fabs expanded capacity, but it also noted that competition is tightening margins. For ACM Research, that environment appears to be creating opportunity and pressure at the same time: opportunity because more processes are being localised, pressure because the market is becoming more crowded and price-sensitive.
The company’s own revenue mix shows how quickly its profile is changing. ACM Research’s China revenue climbed from $541 million in 2023 to $898 million in 2025, while its share of consolidated revenue rose to 99.6%, underscoring how heavily the business remains concentrated in one market. Even so, the company has been growing faster than the market in which it operates. StockAnalysis reported that ACM Research Shanghai’s revenue reached 2.24 billion yuan in the quarter to 30 June 2026, up 14.4% year on year, while full-year 2025 revenue reached 6.79 billion yuan, up 20.8%.
What is most striking is the shift beyond its core cleaning equipment franchise. In the first half of 2026, revenue from technologies outside wafer cleaning surged to $268.7 million, accounting for 51.3% of consolidated sales, compared with 26.6% a year earlier. That growth was driven by electrochemical plating, furnace processing, deposition and advanced packaging-related activity. Cleaning revenue, by contrast, fell over the period. The change suggests ACM Research is no longer just selling a single essential toolset; it is increasingly supplying more of the process steps that Chinese fabs need inside the same manufacturing line.
That broader product base appears to be feeding through into backlog. On 29 September, the company said its Shanghai subsidiary had about $2.5 billion in backlog as of 29 September, up 88.2% from a year earlier. The figure includes orders awaiting shipment and systems already delivered but not yet recognised as revenue under Chinese accounting rules, so it should not be treated as a direct measure of future U.S. GAAP sales. Even so, it indicates that demand remains robust enough to support management’s 2026 revenue outlook of between $1.125 billion and $1.175 billion.
Investors should still be cautious about assuming that stronger sales will translate quickly into stronger profit growth. In the second quarter of 2026, ACM Research reported revenue growth of 36.0% year on year, but non-GAAP diluted earnings per share rose only from $0.55 to $0.61. Non-GAAP gross margin also eased to 46.0% from 48.7%. That gap matters because a company expanding into new equipment categories often has to absorb higher engineering, qualification and manufacturing costs before scale benefits become visible.
The company’s long-term ambitions are more expansive still. Management has outlined a revenue target above $4 billion, including roughly $2.5 billion from mainland China and $1.5 billion from outside the country. Yet that overseas goal is ambitious when set against 2025 sales outside mainland China of just $3.3 million. For now, ACM Research’s strongest position remains in China, where localisation policy, customer qualification cycles and a widening product line are all working in its favour.
The investment case, then, is not simply that China is buying more domestic tools. It is that ACM Research is becoming a more diversified supplier within a market that is actively substituting away from foreign equipment. The company has shown it can grow faster than the overall sector, and its product mix is improving. The remaining question is whether it can turn that momentum into sustained profitability, while managing concentration risk, margin pressure and the operational demands that come with moving deeper into more complex semiconductor processes.
Disclaimer: This content is intended for informational purposes only. Readers are advised to exercise their own judgement, conduct due diligence, or consult a qualified expert before acting on any information provided.