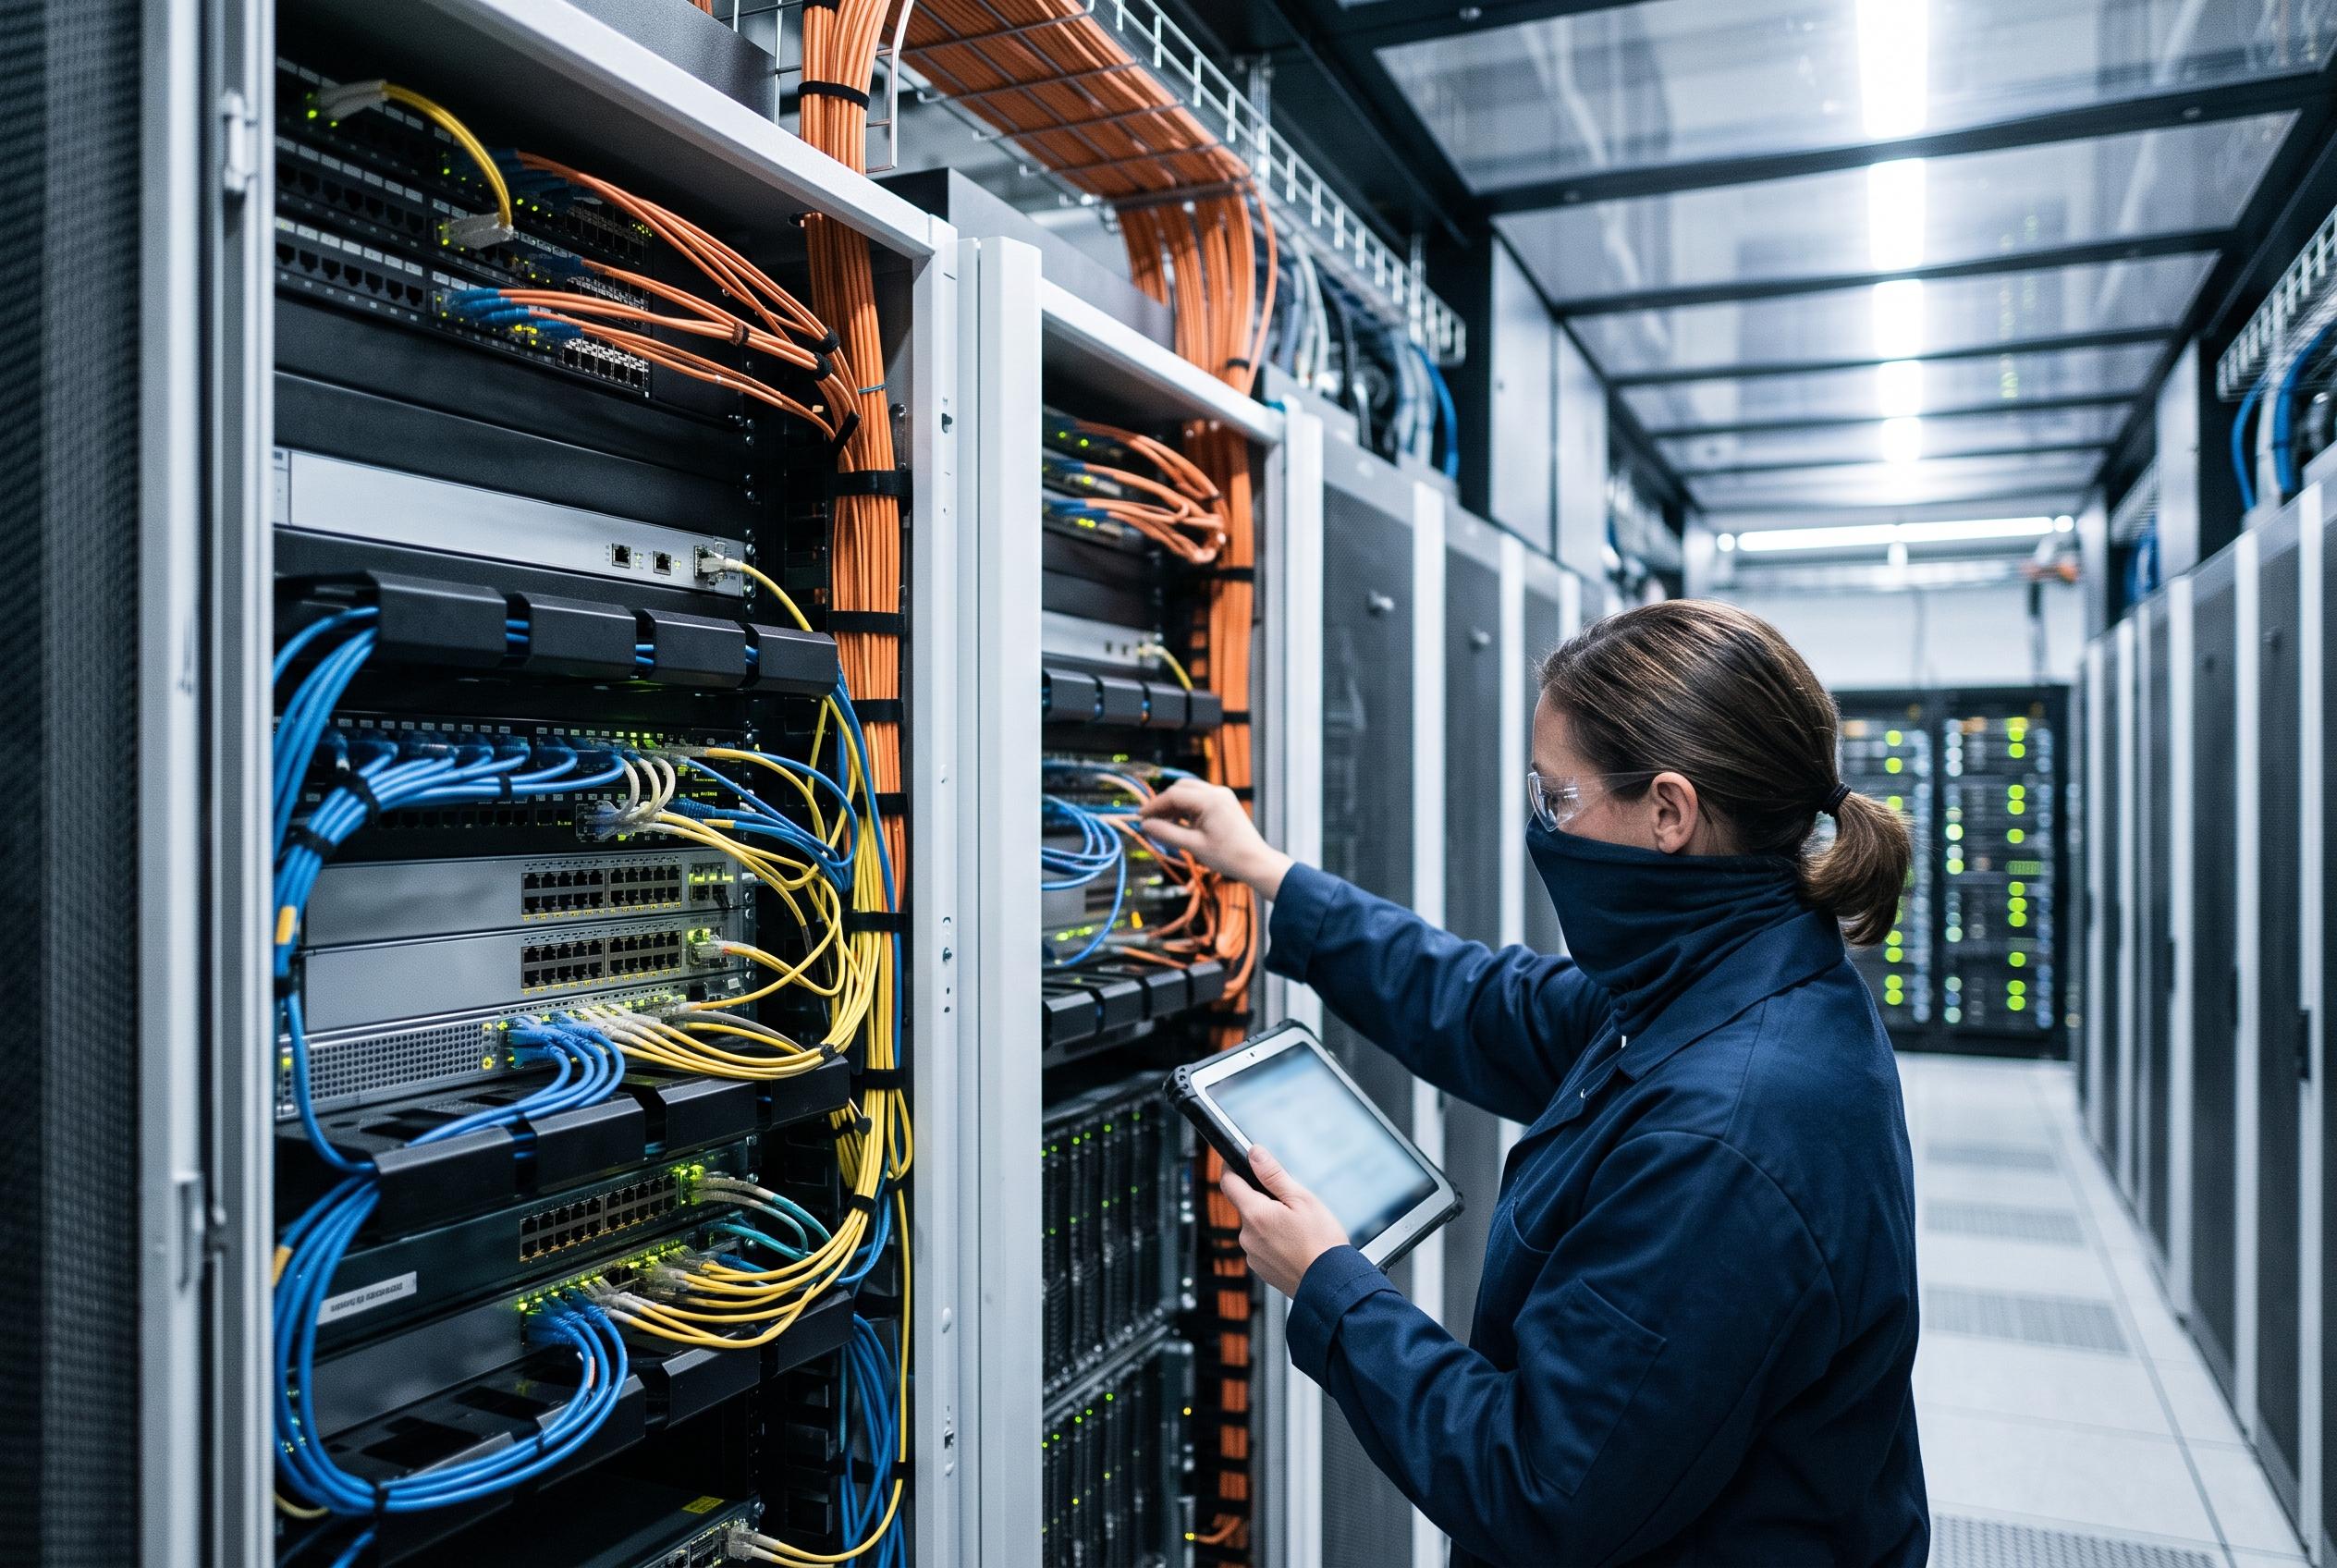

The data centre switch market is experiencing rapid expansion driven by AI workloads, high-performance computing, and evolving technological requirements, with anticipated growth doubling over the next decade amid shifting regional and vendor dynamics.
The data centre switch market is expanding because the network has become a performance limit in its own right. As artificial intelligence clusters scale, switches are no longer simple traffic-management devices; they are now part of the compute fabric that determines how efficiently GPUs, storage and external systems can communicate. In its market study, IG Transformation Partners says the sector was worth $16.84 billion in 2025 and could reach $36.33 billion by 2034, implying steady growth over the rest of the decade.
That forecast sits alongside a wider body of market research that points in the same direction, even if the numbers differ. Grand View Research places the market on a steeper growth path, while IMARC Group and Dataintelo also expect substantial expansion through 2034. The variation reflects differences in scope and assumptions, but the direction is consistent: demand is being driven by cloud build-outs, higher data volumes, AI workloads and the shift towards more distributed and energy-conscious infrastructure.
The technology mix is changing quickly. According to IG Transformation Partners, Ethernet remains the largest switching technology because of its scale, maturity and cost profile, but InfiniBand is the fastest-growing segment as AI training and high-performance computing push demand for lower latency and higher throughput. The same report says ports above 400G are advancing rapidly, with 1.6T systems following 800G more quickly than previous generations. It also notes that switch vendors are adding AI-specific features such as congestion telemetry, multipath support and cluster-aware load balancing, which are increasingly treated as core requirements rather than optional extras.
Regional and segment leadership still reflects the structure of today’s market. IG Transformation Partners says North America accounted for 44% of the market in 2025, helped by hyperscale cloud operators and AI infrastructure investment, while Asia-Pacific held 23% and is expected to grow fastest as digitalisation and new capacity continue. Core switches led the market by type, cloud service providers were the biggest end-user group, and below-100G ports still held the largest installed base. Other research providers broadly agree on the importance of North America, the strength of cloud demand and the rapid rise of Asia-Pacific, even though their estimates for market size and compound annual growth rate differ.
The competitive picture is also shifting. Cisco, Arista Networks, Huawei and NVIDIA remain central names in the sector, but the market is being reshaped by new silicon strategies, open networking demands and acquisitions such as HPE’s purchase of Juniper Networks. IG Transformation Partners says GPU and accelerator vendors entering Ethernet switching are intensifying pressure on established suppliers, while Google Cloud’s Jupiter network is cited as an example of how merchant switch silicon and software-defined networking can support very large-scale fabrics. The result is an industry in which power efficiency, optical compatibility, software flexibility and upgrade timing matter as much as raw port speed.
Disclaimer: This content is intended for informational purposes only. Readers are advised to exercise their own judgement, conduct due diligence, or consult a qualified expert before acting on any information provided.