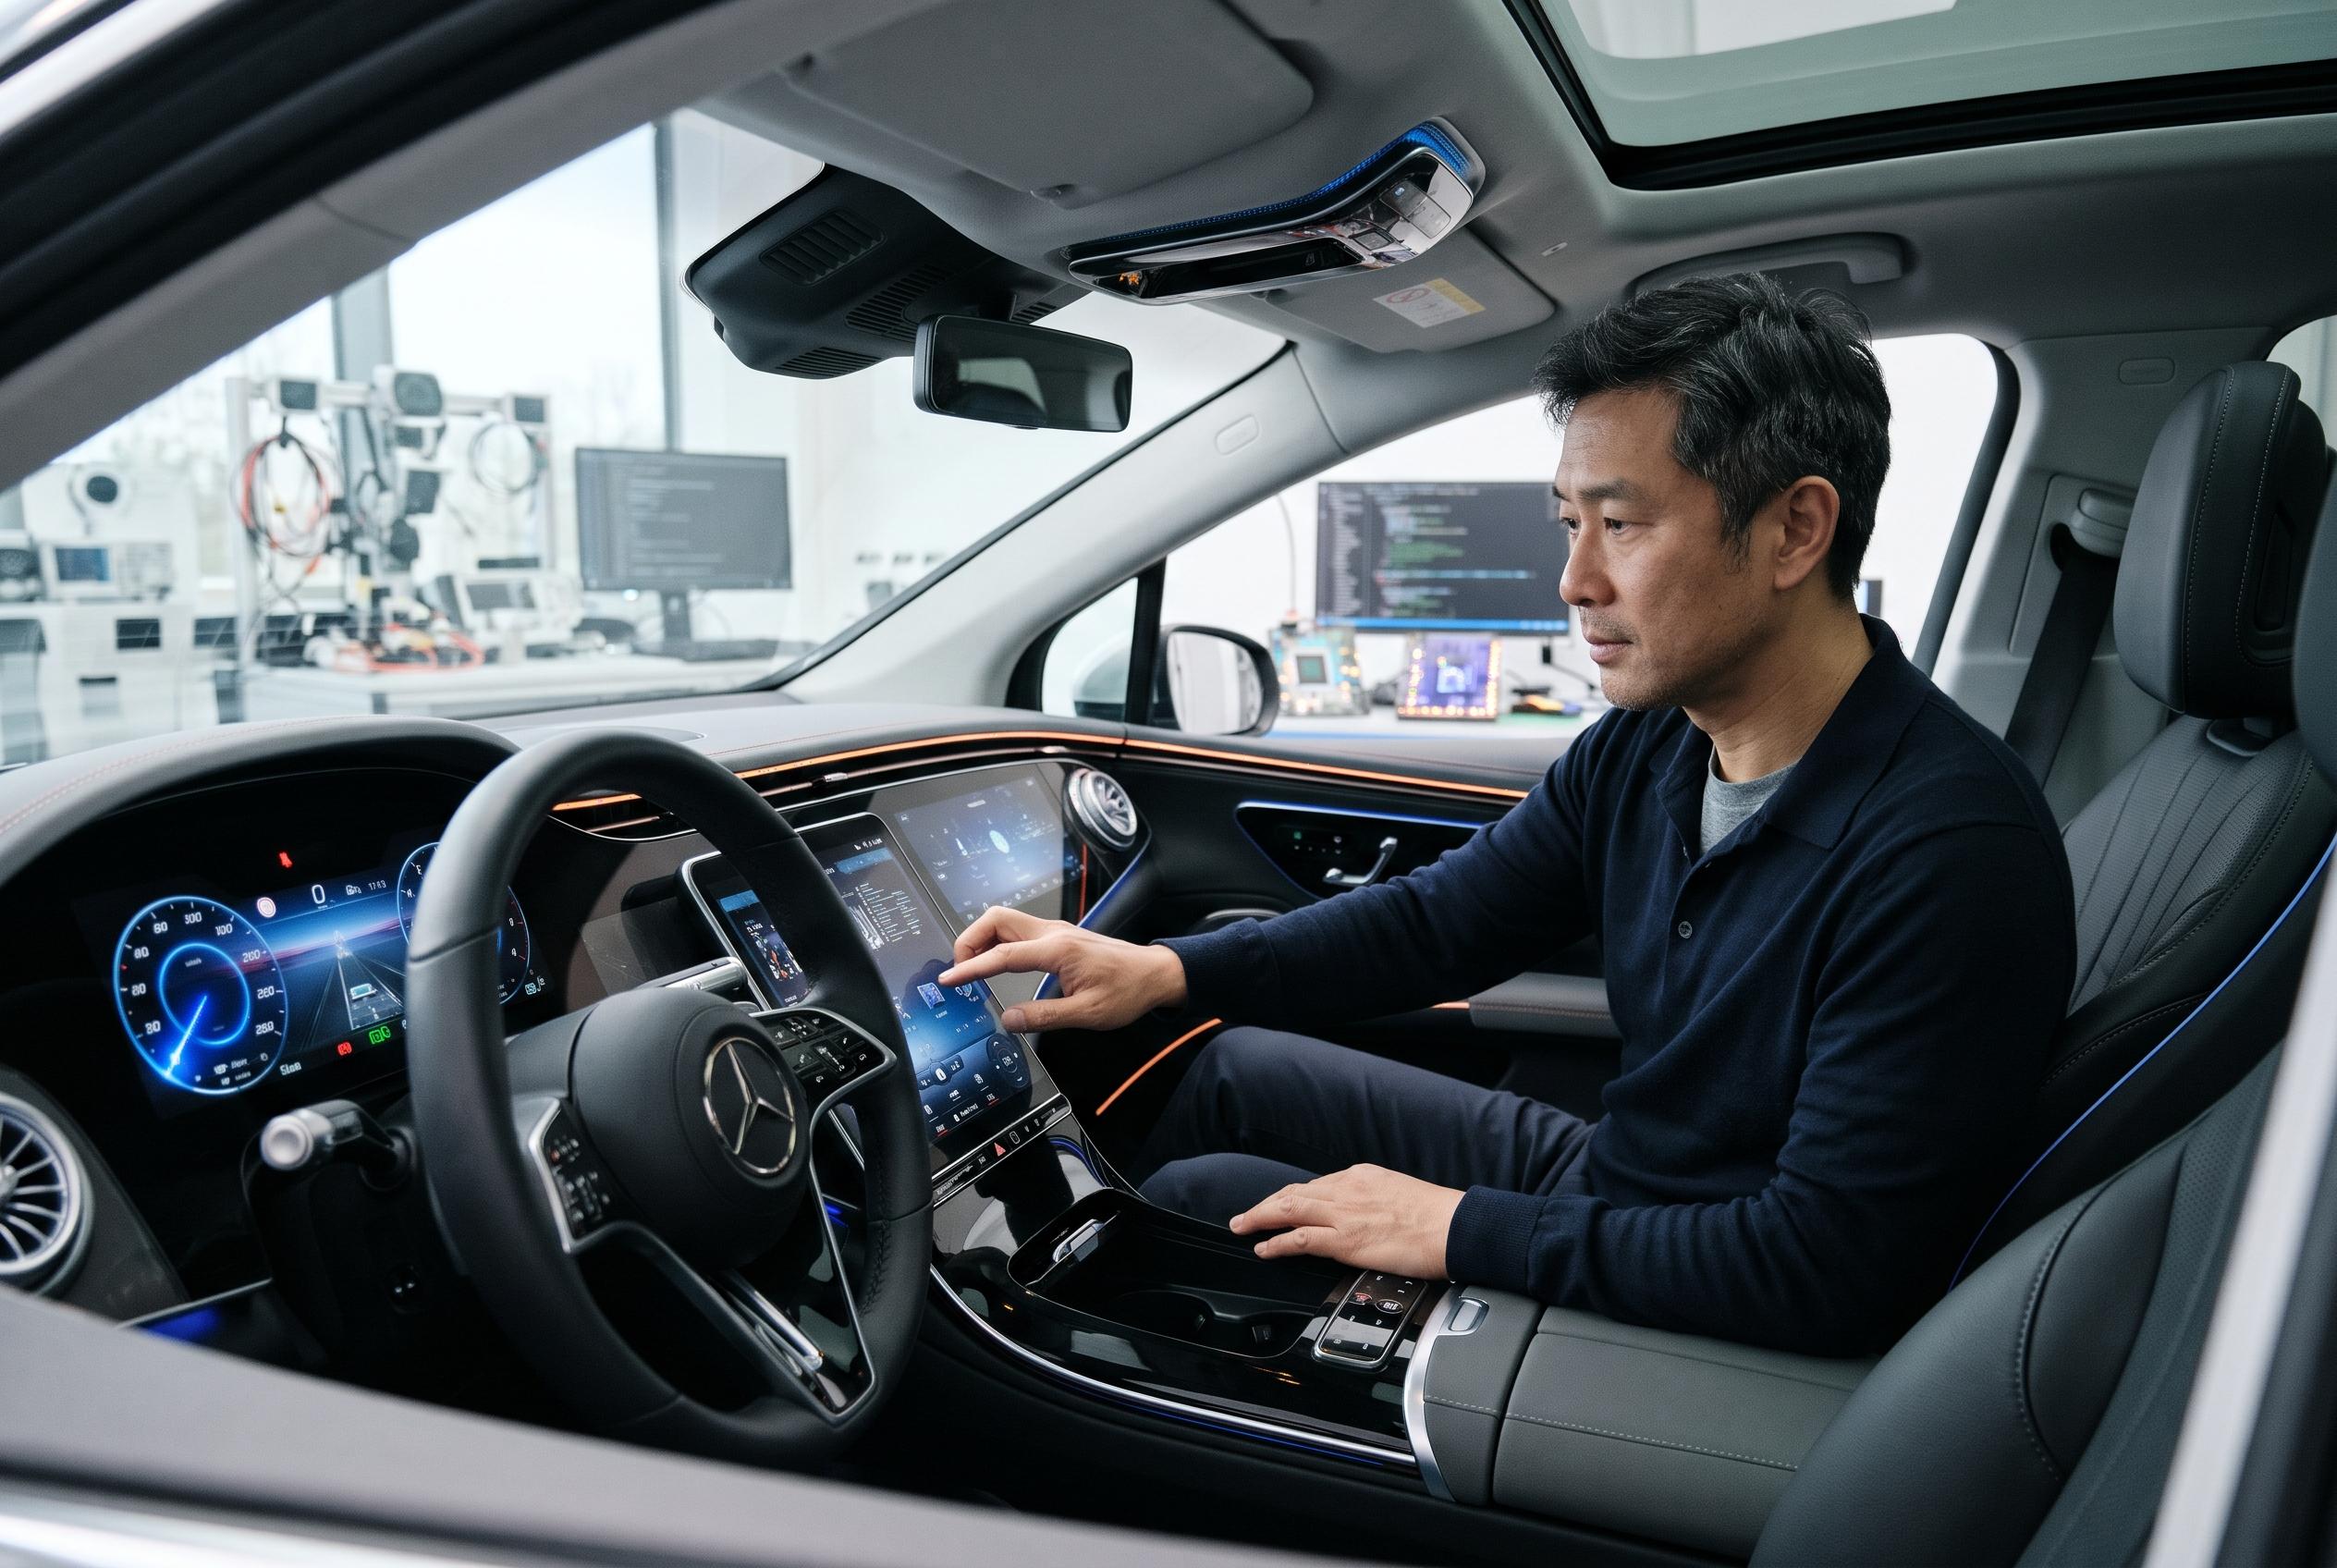

With cockpit architectures hardening, AI entering production vehicles and new safety rules approaching, Chinese suppliers have until 2027 to reduce dependence on foreign chips and software foundations.
The next two years may prove decisive for intelligent cockpits because the industry is moving through three changes at once: platform architectures are being locked in, artificial intelligence is moving into production vehicles, and a tightening regulatory timetable is forcing suppliers to prove compliance earlier than before. At the 2026 China Automotive Supply Chain Conference, Beijing University of Technology professor Wang Chao argued that 2026 and 2027 form a rare opening in which domestic suppliers can strengthen the foundational layers of cockpit systems before interface choices and ecosystem positions become fixed.
That timing matters because China already has scale, but not yet full control of the stack. Gasgoo’s market research says front-install cockpit domain controllers reached 9.85 million units in 2025, with fitment at 42.9%, while single-chip cockpit-and-driving integration platforms also entered mass production. At the same time, CIC estimates that the global smart cockpit solution market for passenger vehicles reached 366.8 billion yuan in 2024 and could almost double by 2029, with China growing faster than the global average. The implication is simple: the market is still expanding, but the battleground is shifting from visible hardware to the software-defined platform beneath it.
Recent market data supports that view. IDC said China’s AI cockpit market reached 710 million yuan in the first half of 2026, with Volcano Engine taking a 45% share, and the firm expects the segment to expand sharply by 2030 as in-car voice, assistants, navigation Q&A, content generation and personalised recommendations move from trial use to mass deployment. Gasgoo’s own research has also shown that domestic suppliers are strengthening their positions across cockpit domains, displays, HUDs and voice systems, even as concentration rises. In other words, the application layer is moving fast, but that progress is exposing deeper dependencies.
Those dependencies are most obvious in the base layer. According to Gasgoo Automotive Research Institute data cited in its 2026 rankings, Qualcomm still held 72.1% of China’s cockpit domain controller chip market in the opening months of the year, while domestic players such as Huawei and SiEngine trailed far behind. Wang’s argument is that assembly share can be misleading: a system may be built locally, yet still depend on foreign chips, real-time operating systems, virtualisation layers and certification tools. That means apparent localisation can conceal a much weaker level of genuine platform control.
The regulatory backdrop makes that weakness more urgent. From 1 July 2026, mandatory national standards on vehicle cybersecurity and software updates apply to newly approved models in China, while from 1 January 2027 the new GB 47955–2026 safety rules for combined driving assistance will require hands-off and eyes-off detection, staged warnings and eventual system disablement. Europe is moving on a similar schedule, with advanced driver distraction warning rules applying to new vehicles in scope from July 2026 and the EU Data Act’s design obligations beginning in September. For Chinese cockpit suppliers, the challenge is no longer only domestic compliance; it is proving that systems can be shipped into export markets with the right evidence chain already in place.
Wang’s prescription is to build for duality rather than dependency. He argues that suppliers should create software platforms that can run on both imported and domestic chipsets, so that migration is possible without rewriting the stack from scratch. For automakers, the priority is to settle next-generation cockpit architectures now, limit hardware sprawl, and keep software architecture, user interaction design and data governance under direct control. For regulators, he says the key task is to support shared infrastructure: common base software, test facilities, certification frameworks and interface standards that would be too costly for any single company to build alone.
The commercial reality is harsh. The auto industry’s average profit margin was just 3.2% in the first quarter of 2026, while storage chips used in cockpits became materially more expensive in the first half of the year. That leaves little room for speculative projects or repeated platform redesigns. It also explains why Wang urges companies to focus resources on mature programmes first, keep a smaller share for growth opportunities and reserve only a limited budget for experimental bets. His broader warning is that China can win share without winning platform power unless it closes the gap in operating systems, chip ecosystems, validation, certification and long-term maintenance.
If the industry uses this window well, intelligent cockpits could become the point at which China moves from component strength to platform strength. If it does not, the country may continue to assemble much of the value chain while the most defensible layers remain controlled elsewhere.
Disclaimer: This content is intended for informational purposes only. Readers are advised to exercise their own judgement, conduct due diligence, or consult a qualified expert before acting on any information provided.